10/16/2026

Are You a Renter? How to Get Past a Loan Qualifying Hurdle

What’s the biggest payment you make every month? If you’re a renter, it’s probably your rent. 

But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It’s pretty frustrating, especially if you’d like to buy a home someday and you’re trying to build your credit.

The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.

The Problem for Would-Be Buyers

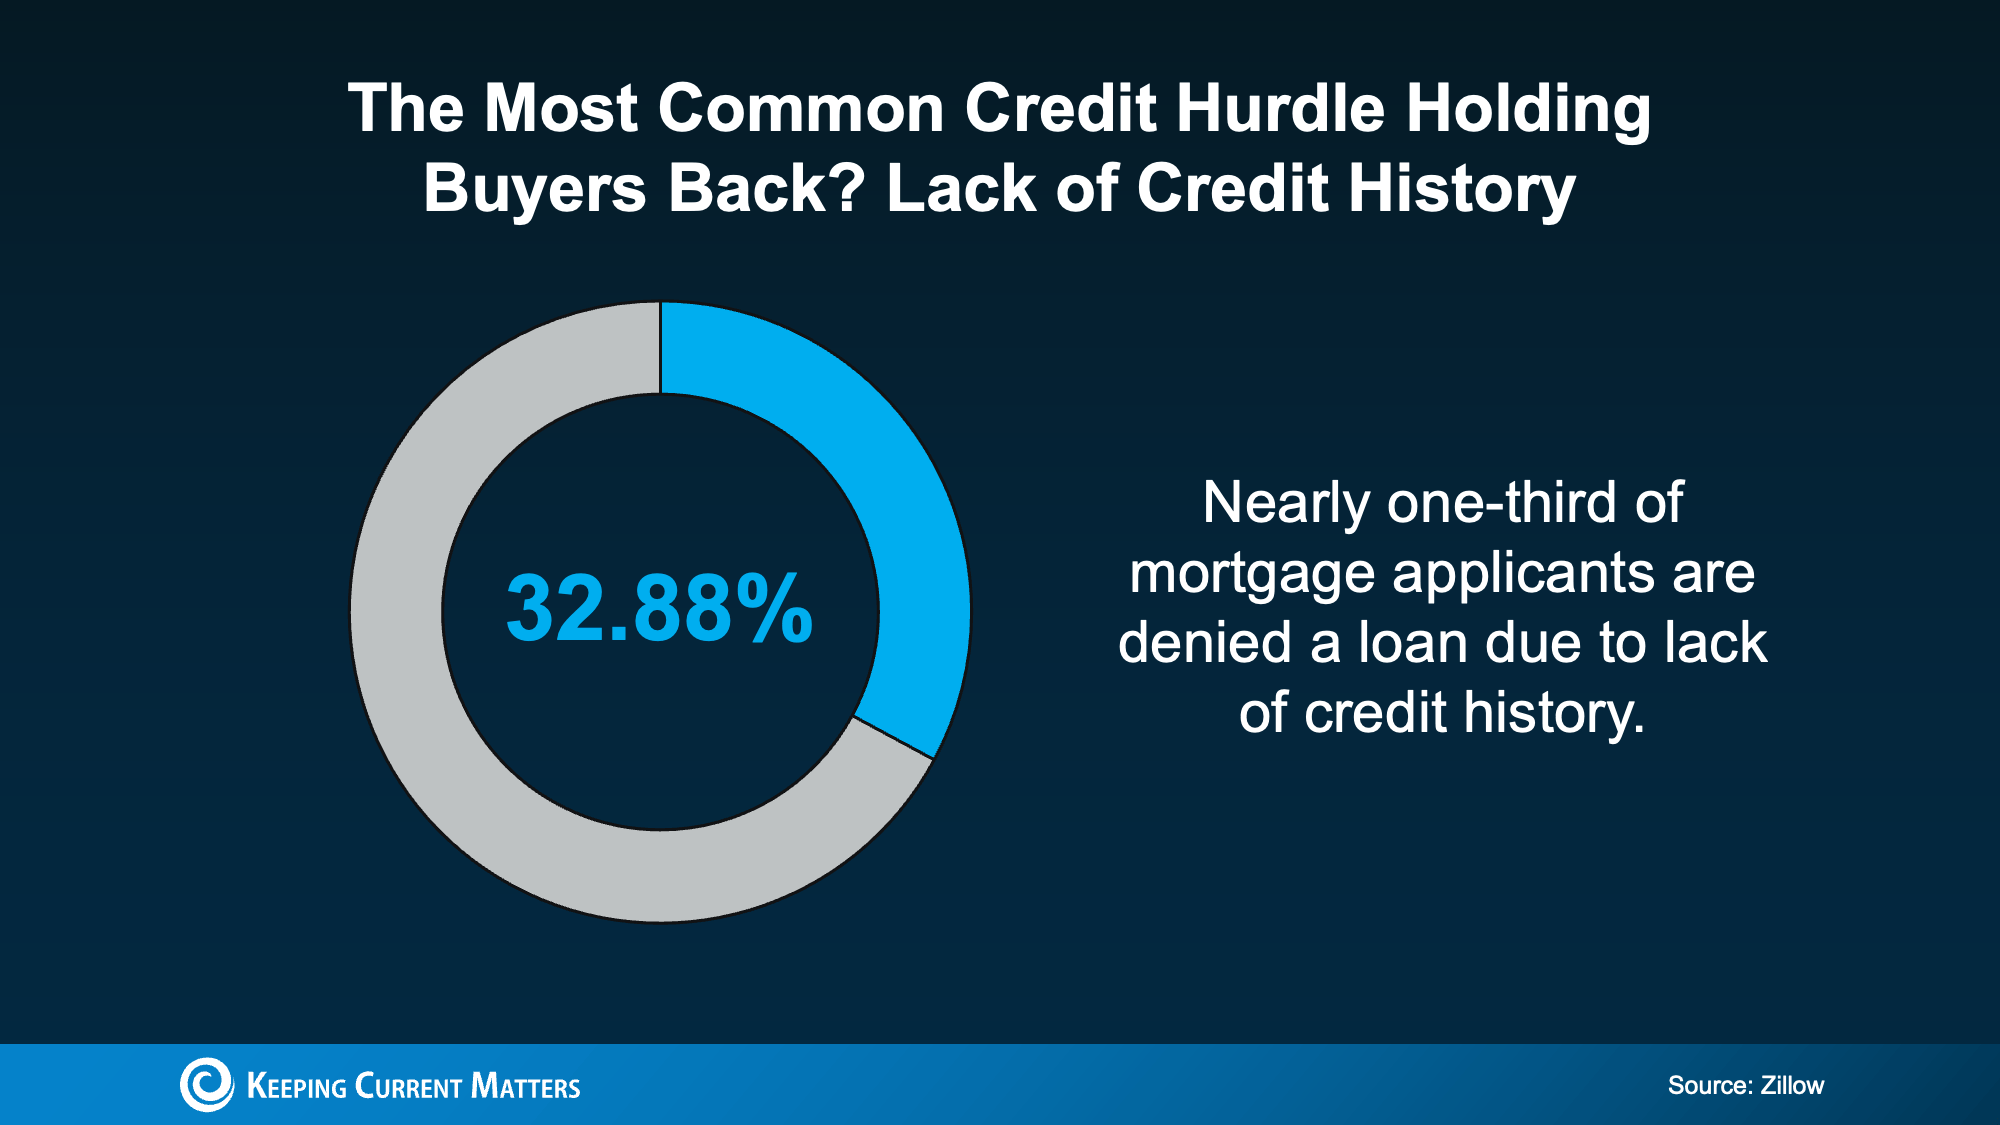
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history – not missed payments or too much debt. Just not enough credit history for a lender to say “yes.”

It’s the most common hurdle would-be buyers have. As Zillow explains:

“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
a blue and grey pie chart

But there’s finally a way in now that how credit gets measured is changing.

The Good News: Credit Is Getting Broader

As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:

“Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”

New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.

VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.

A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.

Here’s the catch though, you still have to walk through it.

How to Get Your Rental Payment to Count

There are more options available to build credit, but you have to be proactive. Your rent won’t necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.

Here’s how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:

  • Ask your landlord or property manager if your rent is being reported. If it’s not, opt in. 

  • If your landlord doesn’t offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.

  • Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.

  • Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don’t apply for a bunch of new credit at once.

  • Don’t close any accounts – even if you have paid them off and don’t use them often.

  • Diversify your profile by getting a secured credit card or becoming an authorized user on someone else’s account to help you build history beyond rent.

These steps take a little time and effort, but it could be worth it if it starts building up your credit history. 

Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better. 

Even if you’re not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.

Bottom Line

The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.

Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you're closer to owning a home than you think.

 If you would like to contact a loan officer, I can refer you to trusted sources.

Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

10/09/2026

The California Housing Market Predictions for 2027

On October 7, 2026 C.A.R. released the market forecast for 2027.  In a nutshell, here is how the median price has been presented at the annual California Association of REALTORS since 2020, and is predicted to continue to rise in 2027, in spite of mortgage rates continuing over 6%:

  • Existing, single-family home sales are forecast to total 277,900 units in 2027, an increase of 3.7 percent from 2026’s projected sales pace of 268,100.

  • California’s median home price is forecast to rise 1.4 percent to $894,400 in 2027, following a projected 0.8 percent increase to $882,200 in 2026 from 2025’s $875,600.

  • Housing affordability* is expected to remain unchanged at 20 percent next year after increasing to a projected 20 percent in 2026 from 19 percent in 2025. 
  •  

     From "C.A.R. releases its 2027 California Housing Market Forecast" 

    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    10/05/2026

    Proposition 37 - Help for New Homeowners in California


    This proposition is up on the ballot for November, and is an opportunity for help with a low 3% down payment to buy a new home up to $1.5 million dollars -- see Secretary of State website https://voterguide.sos.ca.gov/propositions/37/index.htm.

    Proposition 37 does not take money from the State, the $25 billion in bonds are paid back by the mortgage payments of buyers who purchase their homes - - this is not funded otherwise by taxpayers. And unlike other types of buyer assistance programs, there are really no qualifications for this program other than standard mortgage qualification approval, it must be owner occupied, and the purchase must be a NEW home not more than $1.5 million.  And, there is no PMI!

    The buyer must be a California resident and otherwise qualify for the mortgage.  Another benefit from this proposition is that it can stimulate the building of more homes, and give more people the opportunity to buy.

    See https://voteyeson37.com/press-release-yes-on-prop-37-campaign-launches-down-payment-savings-calculator/ in the various counties of the state, where the savings that could be utilized by this program is posted for each county.  Please visit this website https://voteyeson37.com for more complete information about this program, which thus far has received no opposition. It has broad bipartisan support by many California elected officials from all parts of the state. 

     Looking for new home construction near you, even if it's to be built? Please contact me for locations, I can help you, because the MLS and related sites may not offer all location information.

    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    9/28/2026

    The First Interest Rate Hike in 3 Years

    Every two weeks, more or less, California brokers statewide including myself attend and participate in a Zoom call about market conditions, Realtor professional activity, legal counsel advisories, economic updates and other input from our statewide officer leadership. I won't include the entire presentation, but here are two slides from the economic update provided by our Chief Economist of C.A.R.

    9-16-26 Rate Hike
    Seller Motivation to Sell
     

    Contrary to the talk, and hopes, of market sources for many many months, the Federal Open Market Committee met and raised rates on September 16, 2026--with the possibility of another increase before the end of 2026.  What will this mean for buyers and sellers in the future? It means that serious buyers may possibly need to consider which areas are within their consideration, which type of loan will work best for them and investigate conventional, FHA, VA, as well as down payment assistance programs, and considering seller buy down scenarios. Online searches may get you started, but buyers should understand how their credit score and debt will impact the interest rate they may get, and the best way to do this is find an experienced loan officer who will take down all your information and work towards a total loan pre-approval before you start deciding on a particular area or property. Not all lenders work with all down payment assistance programs, for instance, but also may have their own program to offer. Time will be your friend.    

    Sellers also need to consider their options in property pricing, property preparation and negotiation with the buyer and their ability to sell first and buy later. Property showing condition is important to consider if you are looking for the best price, in most situations.  A fixer house in a desirable neighborhood may sell fairly quickly, but if you're thinking of selling a condominium, be aware of potential insurance issues for a buyer, that FNMA is now looking a full HOA document reviews for giving final approval to the buyer, and if all necessary repairs have been completed concerning the common areas. 

     What do you have questions about? I'm here to help!

     Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    8/24/2026

    Long Beach CA Update for Single Family Homes


    In July 2026 there were 136 single family homes listed as sold in the CRMLS, all over Long Beach at an extensive price range from $526,000 to $5,000,000 closing prices.  This post is not otherwise meant to be a comprehensive study, but just to point out some examples of what is going on with some sales transactions as examples of what a seller may experience. 

    Tudor style in Belmont Heights
    An example of a home closing well under original asking price is in the 90814 zip code - Original asking price at $935,000, final closing price at $837,250, with $3400 in costs to repairs from seller to the all cash buyer. The buyer paid their own broker compensation fee.

    Another example is a 90803 property where seller came down  $101,000 to pay both repair costs and the buyer's broker compensation fee, property sold (per CRMLS) at $3,400,000.

    At the lower end of selling prices, in 90807 a home sold with no concessions for compensation fees or repairs at the reduced price from $569,000 to $550,000, on the market for 12 days, buyer paid all cash.

    In 90808, a single family listed at $949,000 and sold at $929,000, and seller paid buyer agent compensation fee plus closing costs amount. Buyer obtained financing and property on market for 33 days.

    Another interesting profile is a home in 90807 that sold in 10 days after listing at $1,225,000, increasing to $1,390,000 and selling at $1,350,000--still at an increased price from the original. Seller paid buyer broker fee as only concession, and buyer obtained mortgage financing. If the home is priced right for the market and is attractive to multiple buyers, then the seller can end up with a net gain. 

     Days on market varied between 0-146 days. While numerous sales show closing higher than list price, upon closer analysis they may also  reflect the increase is due to adding agreed upon repair and agent compensation amounts onto the original price, so that the seller's net is still at or close to the original closing target.

    Eighteen closings were all cash, at all price levels -- from $550,000 to $3,800,000. VA or FHA financing was used in 13 sales. Conventional loans were used in majority of sales.  And sellers are often agreeing  to pay the buyer broker compensation, although that is entirely negotiable and shouldn't be assumed.

    Buyers and sellers need to carefully look at the market because it can be a very selective market at this time, and sometimes a competitive one for the right property.

    For more information for your property, whether it's a house, condo or multi unit, I can help you with my many years of experience. Just contact me via phone, text or email. Thank you for reading. 


    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    8/23/2026

    Reminder: HOA Condo Mortgage Rules Are Changing for Condo Sales

    Pool and spa area of HOA condos

    Effective August 3, 2026, Fannie Mae and Freddie Mac have new rules for their mortgage underwriting in condominium buildings. 

    The California balcony inspection law was one measure enacted after the condo building collapse in Florida just a few years ago. Now Federal Housing Finance Agency (FHFA) is addressing the insurance issues and repairs getting done when reserves are underfunded. 

    There used to be a "limited review process" allowed in as many as 40% of loans nationwide, but no longer. The Full Review process is now required which requires lenders to look at the HOA's financial position, budgeted reserves and owner dues delinquencies.

    The new review process means that the HOA budget must must include the highest reserve allocation in the HOA reserve study (required under California law) to cover costs identified.

    Therefore, starting January 4, 2027, lenders must review the budget and confirm that 15% of annual assessment income is allocated to reserve fund for future maintenance and repairs. That doesn't mean that the entire 15% must actually be in the account, because some may have already been spent for annual repairs, but they must see the 15% allocation in the budget.  This is an increase from the 10% which was in effect for many years previous.

    So buyers and sellers must be prepared for loan approval to take longer than before, and ideally, the HOA property manager will be as prompt as possible in getting the HOA documents to the lender, or the HOA Board will if there is no property manager.  Sellers will want to be aware of timelines and be in touch with their Boards about any compliance issues during this period, and buyers should be in touch with their lenders about any approval questions.

    This is one of the biggest changes to come along in HOA approval process, and this, along with insurance, are reasons for some units needing a little more time to get through escrow. It's important for sellers to know that should their HOA not have the budget properly reflect the 15% reserve amount, as well as outstanding balcony inspection and repair issues, that it may mean a buyer will not qualify for conventional or even FHA loans, until the requirements are met.  

    If you  would like more information about these requirements, this would be a good time to consult with your mortgage lender (some are conducting webinars about this topic), or go to https://singlefamily.fanniemae.com/media/44986/display. 

    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    8/17/2026

    Rent vs. Buying a Condo in Long Beach CA

     Condominiums in Long Beach

    Looking for housing may bring up the question of:  Should I consider buying? 

    Parents of students in college, instructors moving into the area and needing housing soon, or job transfers in the near future all bring up the question of housing.  While there are some long term plans in the works for higher education facilities building their own housing, if you have a much more immediate need, perhaps you might want to consider a purchase if it turns out the monthly payments are close to what a rental would cost. With a condo purchase there's a long term investment potential if you move on, but decide to keep the rental income. 

    Buying a condo has several factors to consider, such as property taxes, monthly dues payment, and insurance costs for condos. Depending on the price of the condo, it's quite possible that the total monthly payment (principal, interest, taxes and insurance plus HOA) may well be comparable to monthly rent. 

    For example, there are currently 25 condo units listed at $3,000/month and under listed for lease or rent in the MLS. These units are all under 1000 sq. ft. and are studios, one or two bedrooms This figure does not include any searches on internet rent sites, or listings with property managers, or any other source, including driving around. 

    There are also numerous condos for sale starting $260,000 near Cal State Long Beach.  Just using this studio with $402 monthly dues as an example, see the cost comparison, buying with a 20% down payment, at the link to a handy calculator comparing renting to condo buying. 

     If you have further interest, or other college areas you'd like to consider searching in, just contact me for information on these properties and information about buying a condominium. This is an avenue come parents have used for student housing, and then had the tax advantages as well. 

     I'm here to help you.

    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    8/08/2026

    The Work of Artificial Intelligence (AI) in California Real Estate Practice

    Buying or Selling with AI?

     AI, as is generally known, seems to be discussed in the media practically everyday. The capacity and use is being expanded on a weekly and/or daily basis. The real estate industry and Realtor organizations are fully aware of the presence and use of AI, including by customers of real estate agents looking to make offers and negotiate transactions. So here are some of the things to consider about AI.

    In response, broker office policies are being developed by brokerages, and on a broader scale, the California Department of Justice has published its legal advisory on the application of California laws to AI. This advisory includes discussion of California's laws on data privacy, unfair competition,  false advertising, competition laws, civil rights, and election misinformation prevention.  And there are recent laws as of January 1, 2025, concerning disclosure requirements for businesses, unauthorized use of likeness, using AI in campaign and election materials, exploitative uses of AI, and AI tools in healthcare settings. 

    Back to the real estate business-- besides advice from the California DOJ, real estate agents are now bound by AB 723, effective January 1, 2026, which imposes new obligations on real estate licensees with respect to the use of digitally altered images in advertisements and promotional materials for the sale of real property. What does this mean? that if a property listing shows photos that have been digitally altered to promote the sale of that property, then the "before" or "actual" view must also be presented with the "improved" altered photos.  In other words, there must be a true representation of the property. Very minor alterations, such as a color enhancement, are not included in this requirement, but a viewer must be able to see the current status of condition. 

    Brokers and agents are currently reporting that customers are asking the AI sites what a good offer price is, how to negotiate some terms, what repairs to ask for when the physical inspection report is uploaded for AI review, etc.  Many agents are using AI in their work, including myself, there are many ways it can be very helpful, but please note that AI can make mistakes, and that is noted in the summaries/responses that I've received back to a request or question.  

    Things to keep in mind when using AI for real estate: a) it hasn't been inside the houses in the area for comp purposes; b) at this moment in time, it doesn't know all real estate law, customs or broker practices, either statewide or locally; c) it doesn't set up appointments and show the customer the property; d) it may not do a complete job on reviewing seller disclosures or other documents nor know what may have been omitted/delayed/is incomplete; e) it may miss a major issue, or one that becomes a major issue for the client, in any of its summaries (back to that disclosure about mistakes). The real estate agent, who is there to help the client, is the agent for the client per their contract with each other, and is not the agent of AI, which is an outside 3rd party to which it has no obligation. 

    In the meantime, AI tools are rapidly being added to the agent's toolbox to create ease and convenience in certain ways for getting documents prepared. But these tools are not just picked out of the sky, they have been vetted and reviewed by our professional organization to keep clients at the forefront. So prospective buyers should be aware that while AI is amazing, it's a tool, and one which can be used successfully by both you and your agent in the right ways. And now, I'm going to ask AI for a nice illustration for this post.


     Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    7/21/2026

    California Sales and Price Report for June 2026 Single Family Homes

    Calif Sales and Price Report 6-2026

    • Southern California had a 10.8 percent year-over-year increase in home sales.
    • Southern California had a 2.3 percent year-over-year gain in median home price.
    • Housing inventory statewide declined from 3.8 months last year to 3.1 months in June, 2026 . Looking ahead, housing supply is likely to remain constrained in the months ahead.
    • The 30-year, fixed-mortgage interest rate averaged 6.49 percent in June, down from 6.82 percent in June 2025, according to California Association of Realtor's calculations based on Freddie Mac’s weekly mortgage survey data. 


    Calif Regional Sales and Price Activity 6-2026

    The Central Coast and Far North areas of California had largest year-over-year median price increase and largest increases in sales volume for single family houses.

    Per C.A.R.: 

  • "Existing, single-family home sales totaled 279,880 in June on a seasonally adjusted annualized rate, up 4.1 percent from May and 6.0 percent from June 2025. 
  • "The statewide median home price declined to $904,640, down 2.8 percent from its record-breaking price of $930,260 in May, but up 0.4 percent from $901,310 in June 2025.
  • "Year-to-date sales increased 1.9 percent."
  •  

    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    7/17/2026

    Did You Get an Unsolicited Text from Someone Offering to Buy Your House?


    Did you receive an unsolicited text, or letter, or drive by a sign in your area from someone saying "we buy houses"? These are usually the work of  wholesalers. There's a California bill now attempting to address this issue, where a home is purchased quickly, and the seller may think conveniently, without having to do repairs, by an unlicensed person or persons who offer you an easy "no commission" deal. 

    The bill AB 1850 is still under consideration, and it addresses some vital issues to protect sellers.  As stated by California Association of Realtors, which is backing the bill: 

    AB 1850 requires individuals engaged in real estate wholesaling in California to be licensed by the Department of Real Estate. Wholesalers routinely perform activities that mirror traditional brokerage activities. They solicit property owners, negotiate purchase agreements, market contractual interests for profit, and facilitate the transfer of residential property interests, all while operating outside the state's licensing and consumer protection framework. Because wholesaling is not expressly addressed under current law, ambiguity exists and consumers are left without the safeguards that apply to licensed professionals. This gap has created opportunities for abuse, particularly targeting vulnerable or distressed homeowners, and has enabled misleading marketing practices and transaction structures designed to avoid accountability. AB 1850 addresses these issues by bringing wholesaling activity within the Department of Real Estate's licensing authority, ensuring that those who arrange and profit from real property transactions are subject to consistent professional standards and oversight. 

    Some wholesalers are even attempting to procure properties that are already on the market and under contract with a listing agent (and some are even other licensed agents, I'm told). This is becoming more frequent in Northern California right now.  A property owner who does not have much of a budget for repairs, or has inherited a property that needs work, may be tempted to work with such offers. But just look down the road when it goes back on the market, sometimes with minimal work done, for much more than it was purchased for. 

    Key provisions in the bill are 1) wholesalers must be licensed; 2) wholesalers must disclose in writing they are not taking title to the property; 3) the definition of wholesaling as the intent to buy the property with the intent to sell, assign or market the contract to another person or entity for profit or compensation; 4) engaging in wholesaling with out license is a criminal offense. This bill requires that wholesalers be transparent about their intentions, reduce fraud, and increase accountability in the real estate market.

    If you would like to know more about the market value of your home or property, I'm available by email, phone or text, as a licensed Realtor and broker. 


    Julia Huntsman, REALTOR, Broker | http://www.abodes.realestate | 562-896-2609 | California Lic. #01188996

    Web Statistics